
Unitranche financing has gone from a niche alternative to the default structure for a large share of mid-market sponsor-backed deals over the past decade. Standardization at that level tends to make people assume the structure itself is now a solved, uniform product. In practice, the label "unitranche" covers a wide range of economic and governance outcomes, and the specific terms negotiated inside it still meaningfully affect risk and recovery.
What unitranche standardized, and what it did not
The unitranche structure solved a real problem: it collapsed a first lien and second lien into a single facility with a blended rate, simplifying the capital structure and giving the sponsor one lender relationship instead of two. What it did not standardize is the agent-among-lenders arrangement (AAL) that governs how the first-out and last-out tranches within that single facility actually behave relative to each other.
The agent-among-lenders agreement is where the real terms live
The AAL is typically a bilateral agreement between the first-out and last-out lenders, invisible to the borrower, and it is where most of the economically significant negotiation actually happens.
- Waterfall mechanics determine exactly how proceeds get split in a workout, and small differences here can meaningfully change recovery outcomes.
- Voting and control rights determine who directs a restructuring process, and last-out lenders without meaningful voting rights can find themselves with less influence than their capital-at-risk would suggest.
- Buy-out rights, where the first-out lender can be required to sell its position to the last-out lender at par plus accrued interest in a default scenario, shift who ultimately controls the workout.
Terms that still vary widely deal to deal
Beyond the AAL, several structural elements remain genuinely negotiated on each transaction rather than following a fixed market template.
- Most favored nation (MFN) protection, and how long it lasts and what triggers exempt future incremental debt from it.
- EBITDA add-back conventions, particularly around cost synergies and run-rate adjustments for acquisitions that have not yet closed.
- Financial maintenance covenant levels and cushion, since unitranche deals more often retain a maintenance covenant than the broadly syndicated market.
- Portability provisions that let a sponsor transfer the existing facility to a new owner without triggering a change of control repayment.
Why this matters more in a slower growth environment
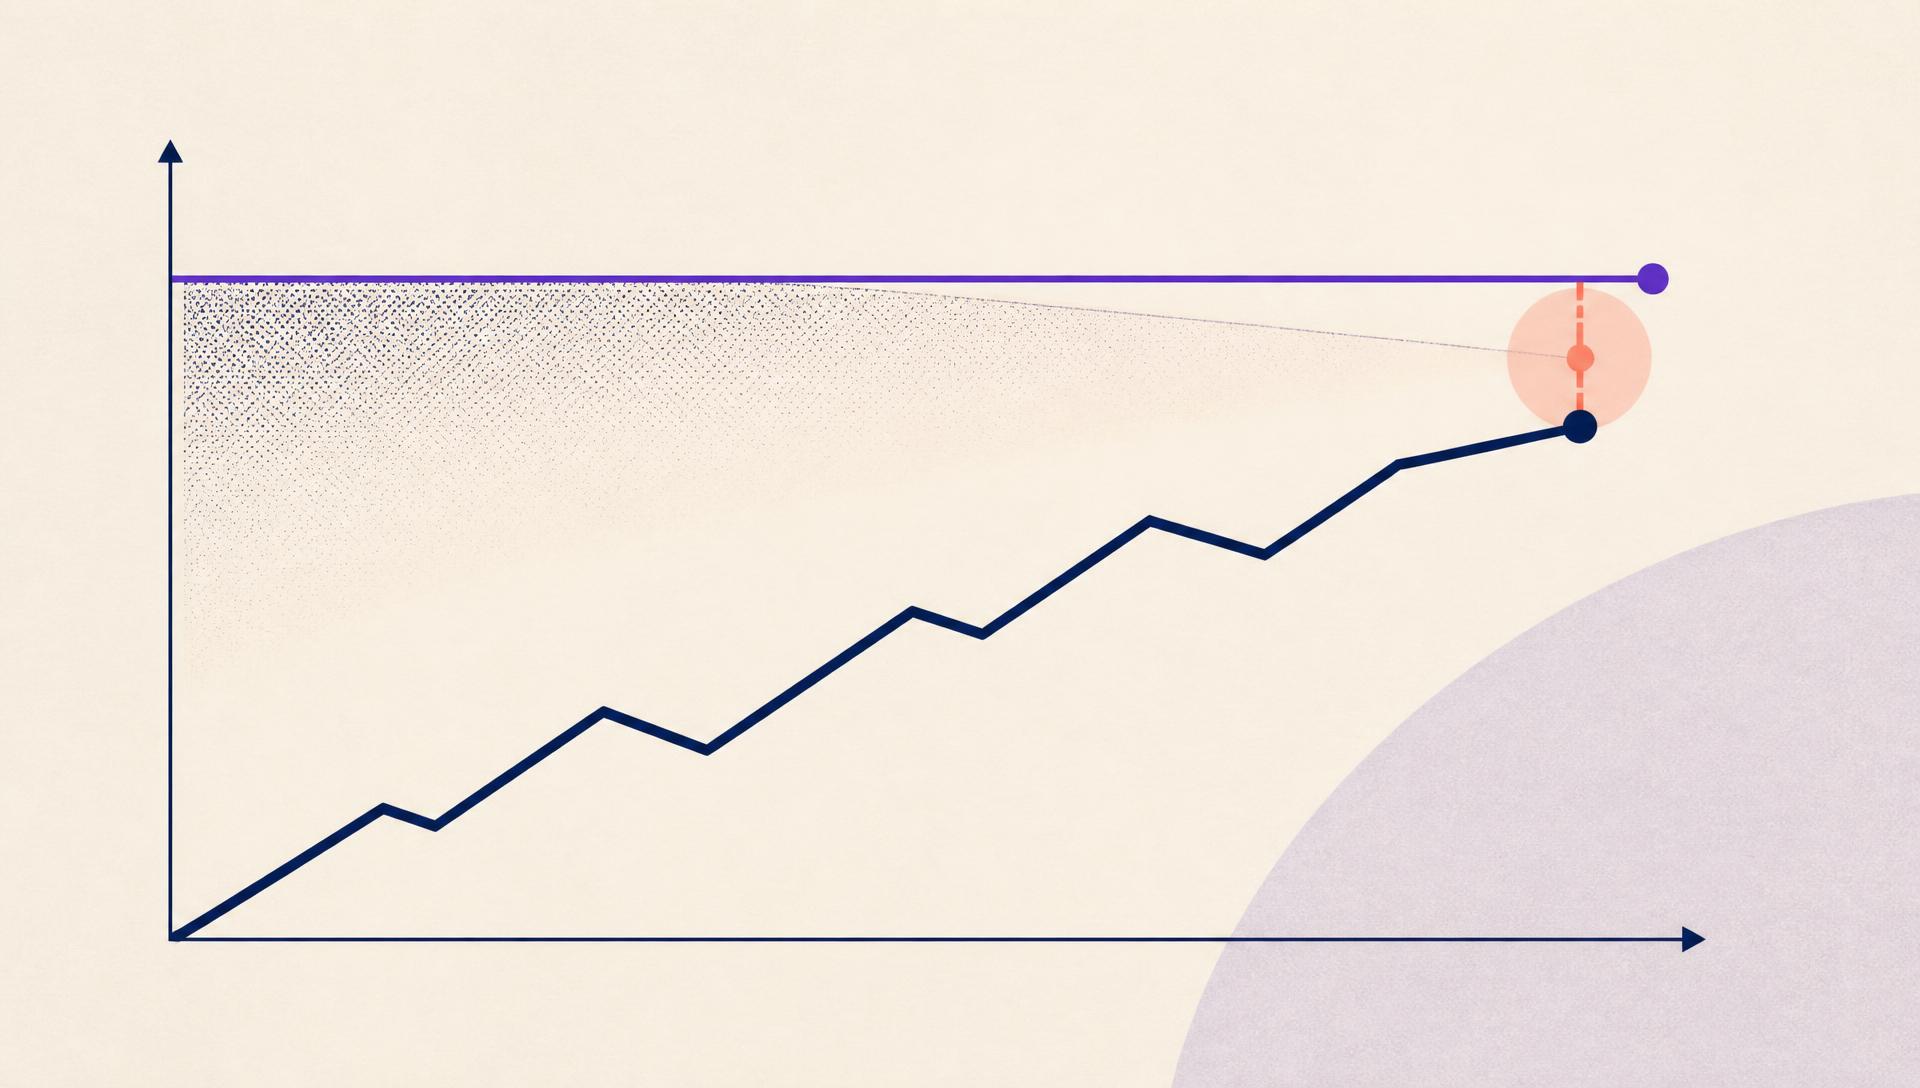
When portfolio companies were reliably growing into their leverage, the fine print of an AAL rarely mattered because loans performed and refinanced without incident. In an environment with more credits under stress, the specific mechanics of first-out and last-out priority, and who actually controls a restructuring, become directly relevant to recovery rates rather than a theoretical concern.
The word unitranche describes the borrower's experience of the facility. It says very little about what happens between the lenders if things go wrong.
What lenders should be tracking across a portfolio
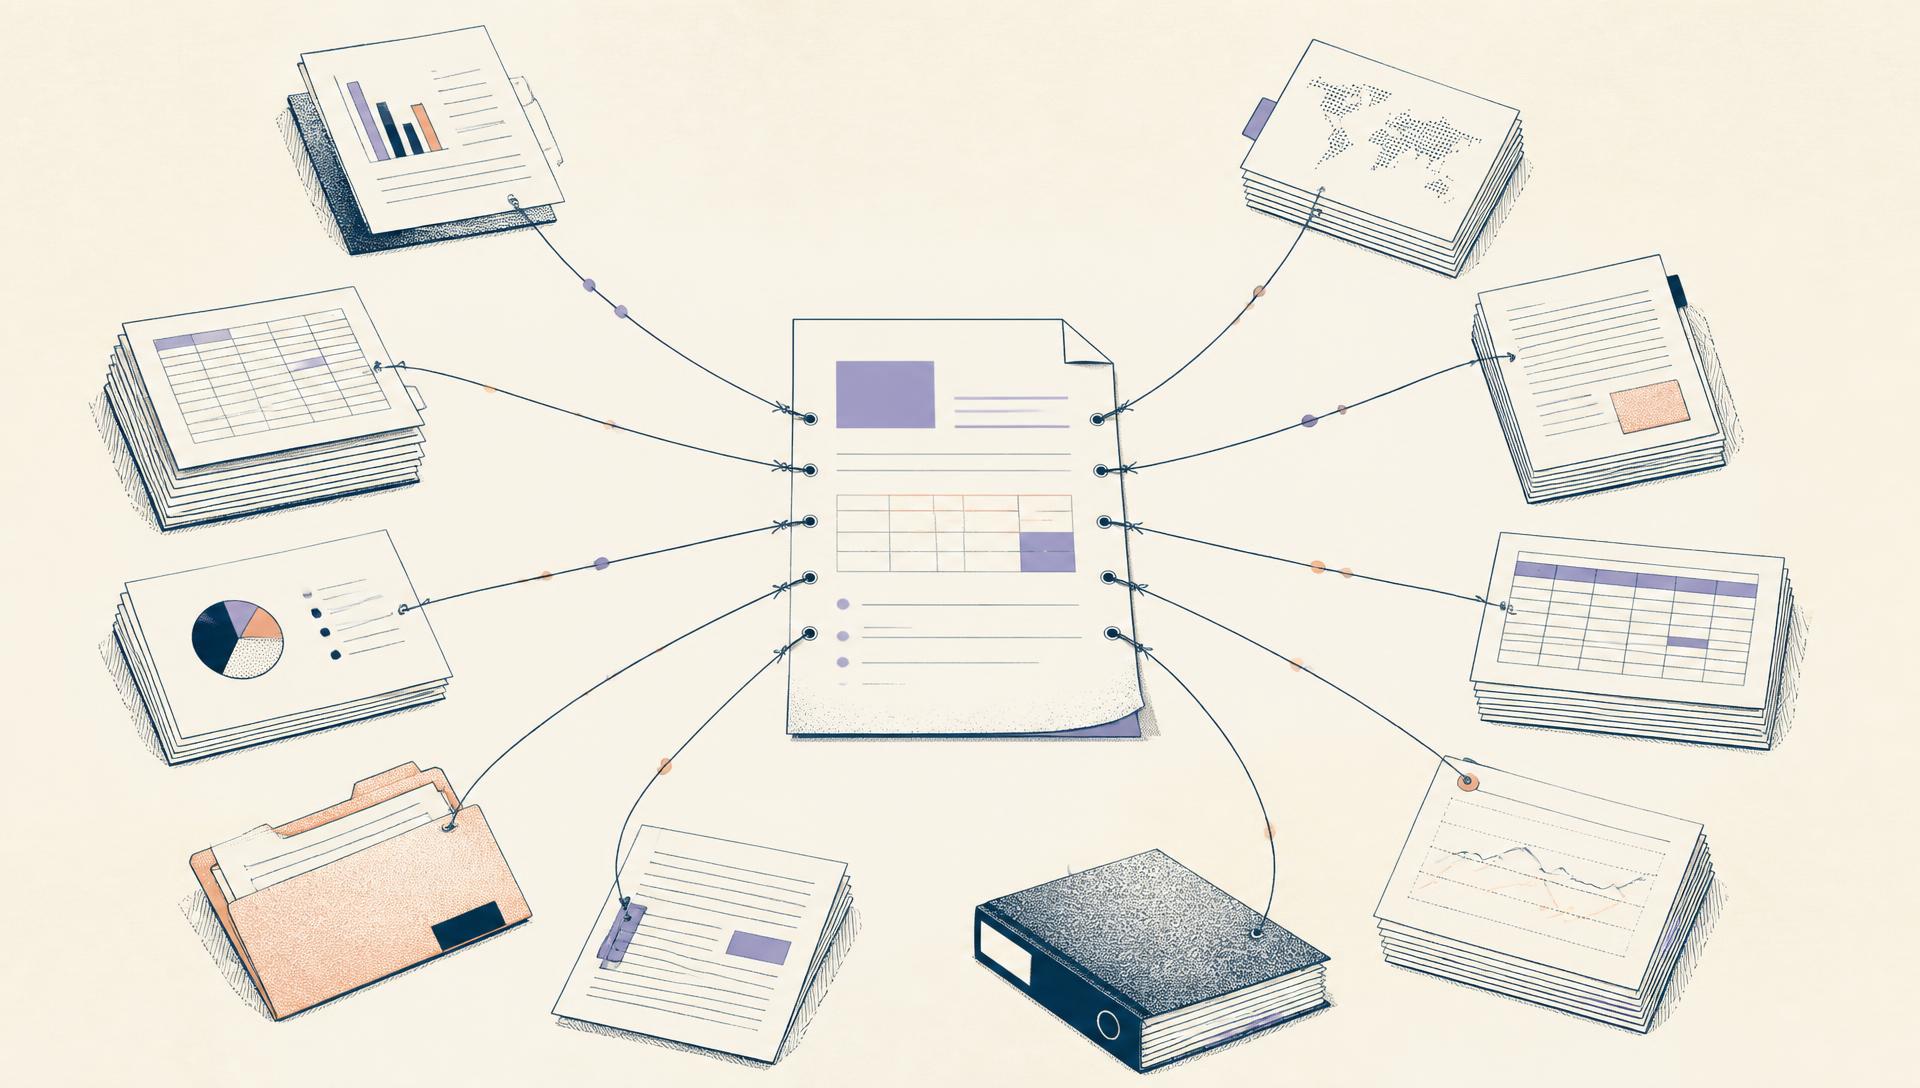
For a lender active in unitranche structures across many deals, the practical challenge is keeping the specific AAL terms, MFN provisions, and covenant levels for each deal accessible and comparable, rather than filed away and re-read only when a problem surfaces.
- Maintain a structured record of each deal's first-out and last-out split, voting thresholds, and buy-out mechanics.
- Track MFN triggers across the portfolio so incremental debt decisions on one deal do not create unexpected obligations on another.
- Compare covenant cushion across vintages to identify where earlier deals may be more exposed than recent underwriting standards would allow today.
The underlying point
Standardization of a structure's name does not mean standardization of its substance. The lenders who do best in unitranche, particularly in a workout, tend to be the ones who read and tracked the AAL as carefully as they read the credit agreement itself, and who can retrieve those terms quickly when a portfolio company starts to show stress.