
Asset-based lending has a reputation for being the safer end of the credit spectrum, because every dollar advanced is tied to a specific, identifiable piece of collateral, accounts receivable, inventory, equipment. That reputation is largely earned, but it obscures where ABL lenders actually take losses. It is rarely the structure. It is almost always the monitoring.
The borrowing base is a moving target
A borrowing base certificate is a snapshot, produced by the borrower, of eligible collateral on a given date. Eligibility rules, ineligibles for aged receivables, concentration caps on any single customer, exclusions for slow-moving inventory, exist precisely because collateral value erodes in specific, predictable ways as a business deteriorates.
Where the process typically breaks down
- Borrowing base certificates are accepted at face value without independent verification against the underlying receivables aging or inventory schedule.
- Field exams happen on a fixed calendar schedule rather than in response to deteriorating trends that would justify more frequent review.
- Ineligible collateral, aged receivables past the eligibility threshold, is not consistently flagged and excluded before an advance is calculated.
Why this matters more as a credit weakens
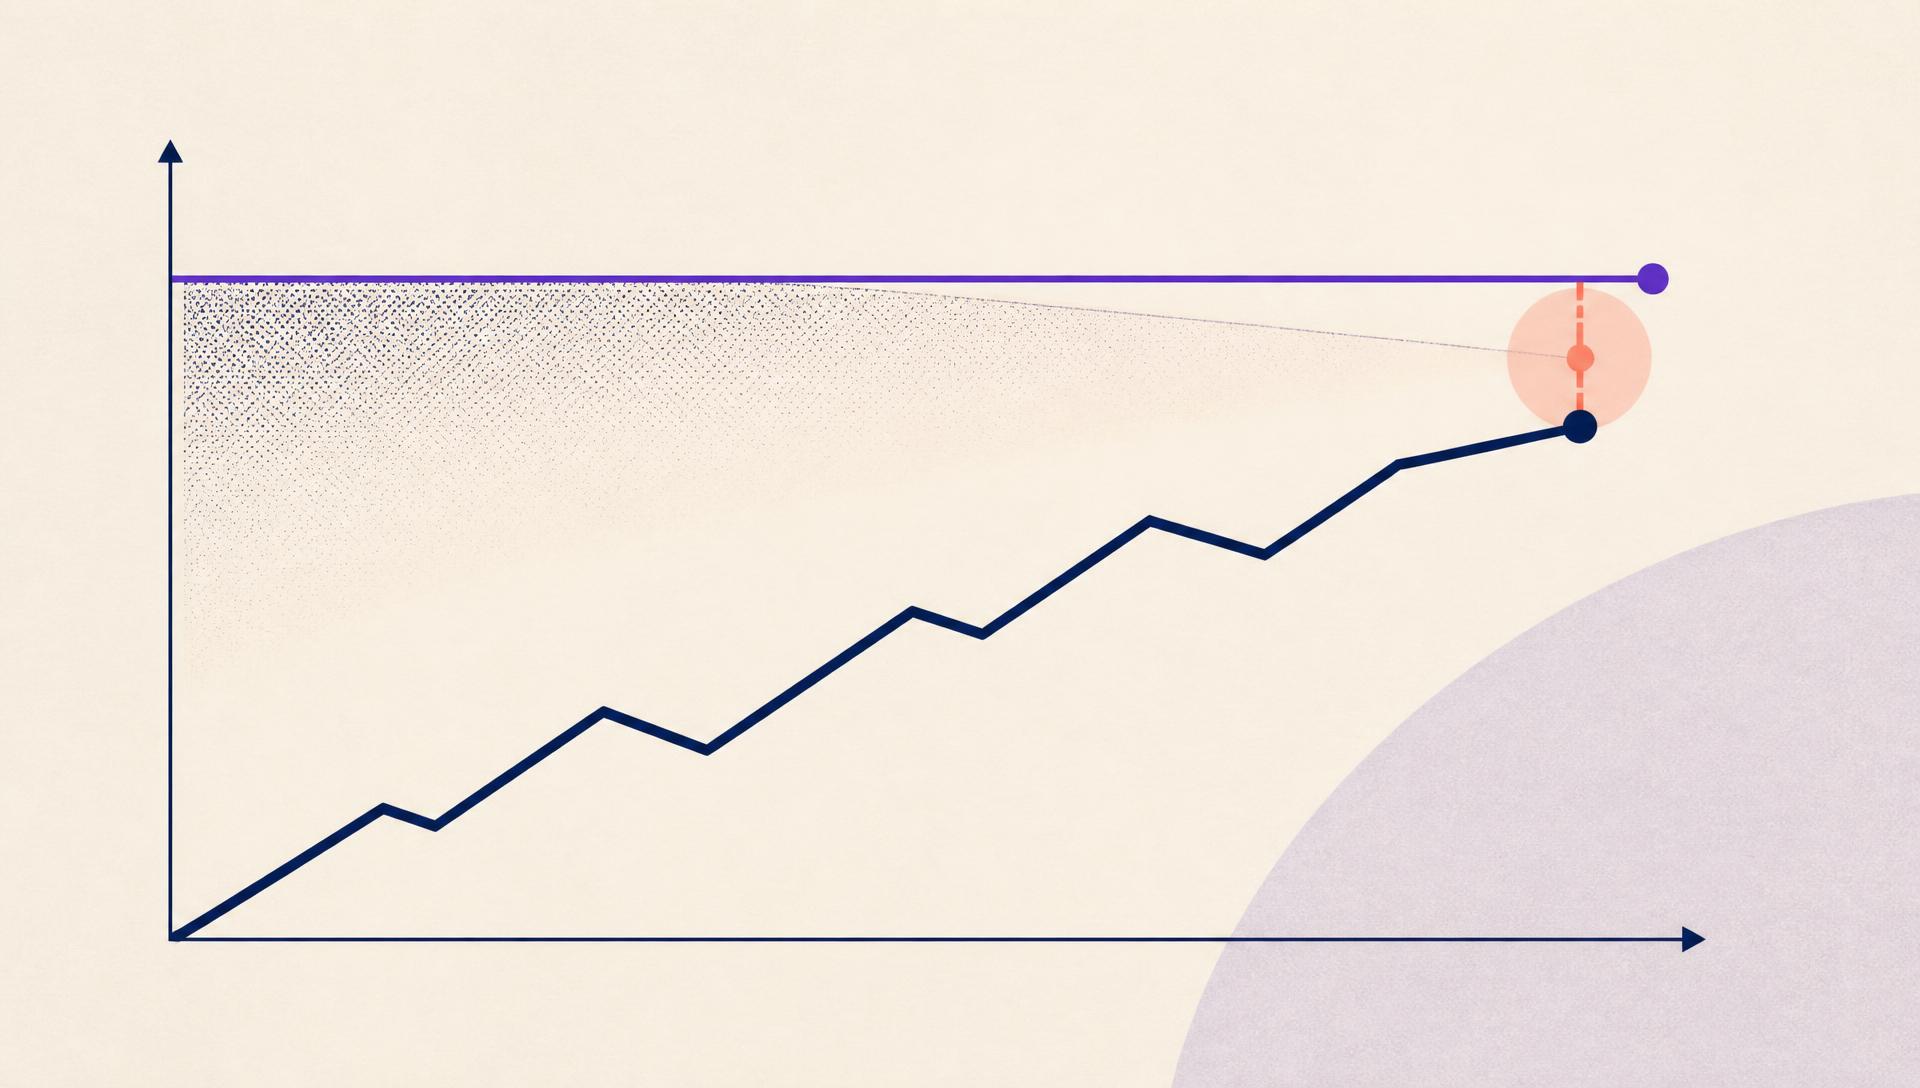
A healthy borrower's borrowing base certificate is usually accurate, because there is little incentive to misrepresent collateral when the business is performing. The risk concentrates precisely when a borrower is under stress, which is also exactly when the temptation to overstate eligible collateral, intentionally or through simple lag in updating aging schedules, is highest.
The borrowing base tells a lender the least when the lender needs it to tell them the most.
What disciplined monitoring looks like
Independent verification of eligibility
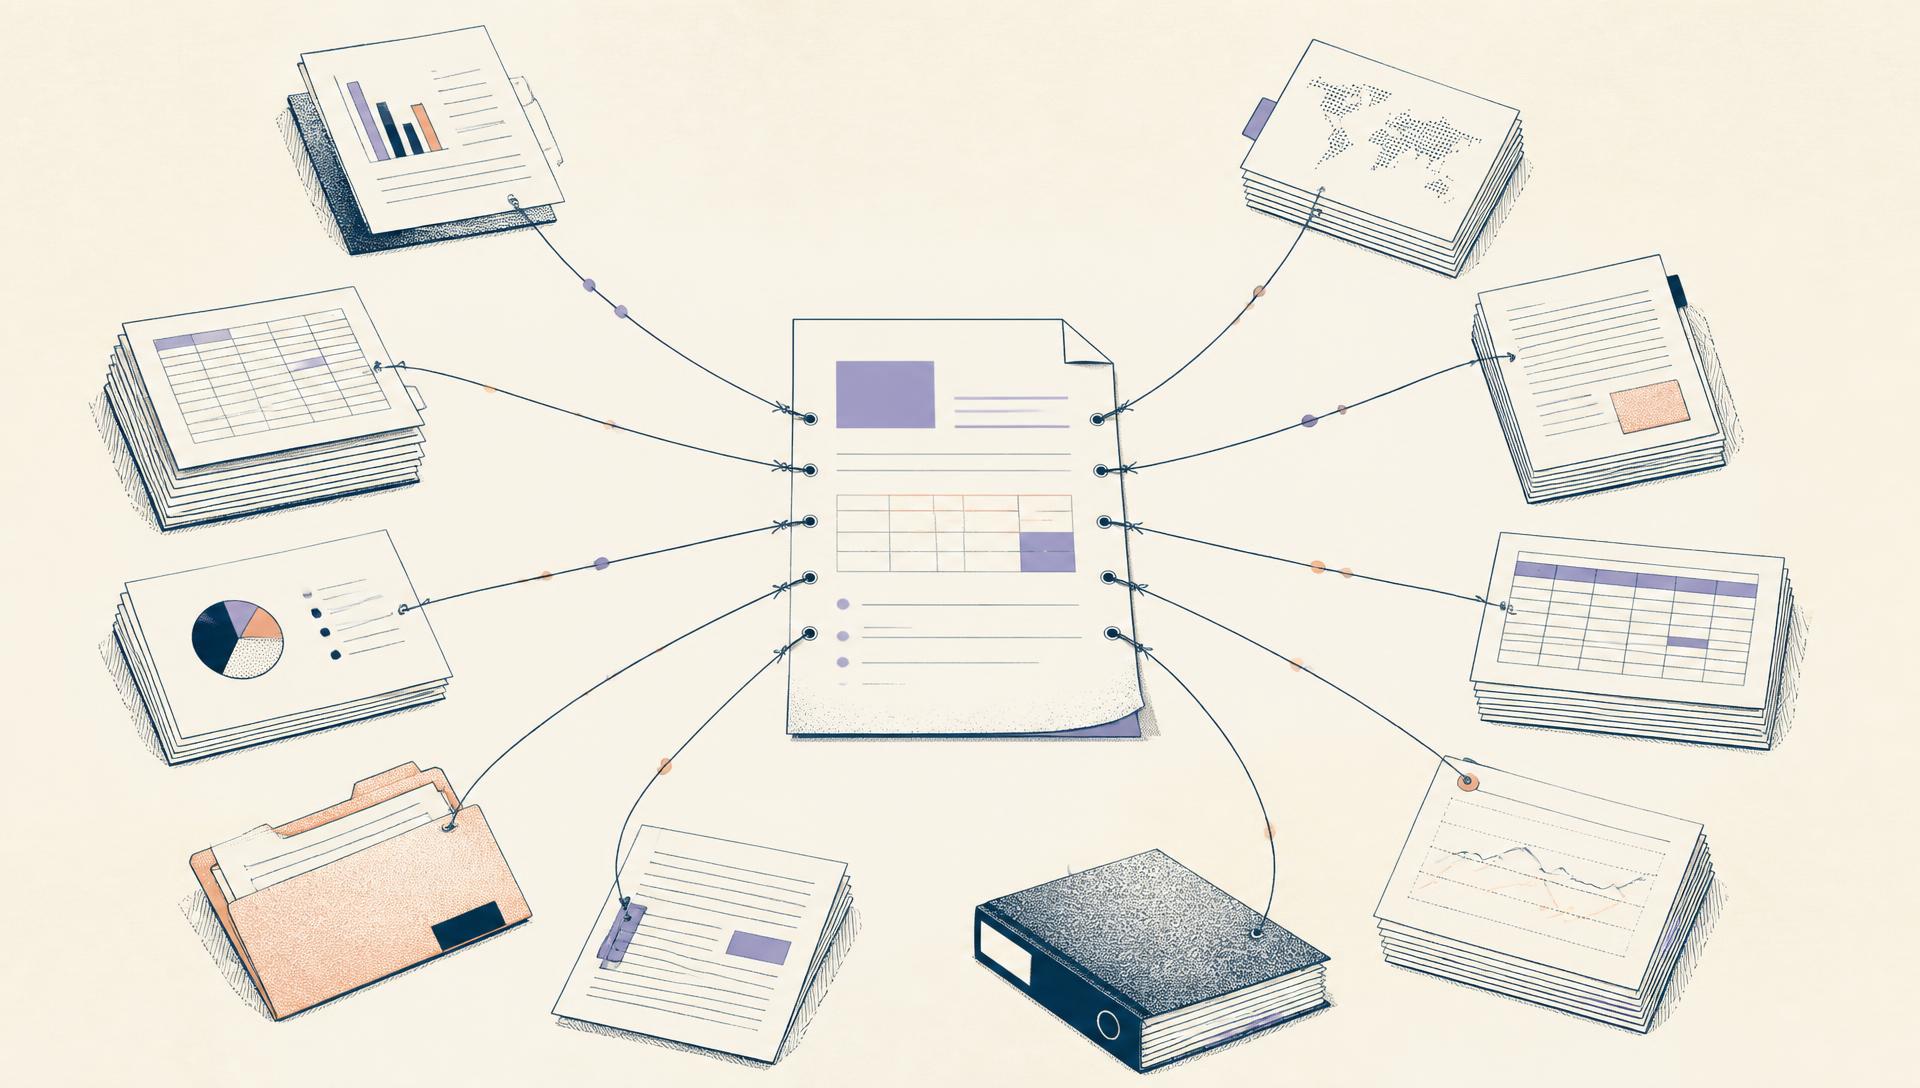
Rather than accepting a borrower's self-reported eligible collateral figure, a disciplined process reconciles the certificate against the underlying accounts receivable aging report and inventory listing, checking that concentration limits and aging exclusions were actually applied correctly.
Trend analysis across certificates
A single borrowing base certificate tells a lender the collateral position on one date. A time series of certificates tells a lender whether receivables are aging out faster than usual, whether a single customer's concentration is creeping toward the cap, or whether inventory turns are slowing, all of which are early indicators of stress well before a covenant is breached.
Field exam frequency tied to risk, not calendar
Fixed quarterly or annual field exam schedules make sense for stable credits, but a lender should be able to trigger an exam off of specific trend signals, a spike in dilution, a slowdown in collections, rather than waiting for the next scheduled date.
Building the infrastructure for this
Manual reconciliation of borrowing base certificates against aging schedules, done in spreadsheets by an overstretched portfolio team, does not scale past a modest number of borrowers, and it is exactly the kind of repetitive, document-heavy verification work that benefits from structured extraction and automated cross-checking.
- Extract aging and concentration data directly from receivables schedules rather than trusting summary figures.
- Automatically flag certificates where reported eligible collateral diverges from the reconciled figure.
- Track concentration and aging trends across every borrower in the portfolio, not just the ones already flagged as watch list credits.
The lesson
ABL lending is not safer because the structure is simpler. It is safer only when the monitoring keeps pace with how quickly collateral value can erode, and the lenders who lose money in this asset class are almost always the ones who mistook a well-structured borrowing base for a self-monitoring one.